2 min read
The Most Important Insurance You Should Have...
Thomas von Finanzfluss explains private liability insurance, widely considered the most important non-mandatory insurance.
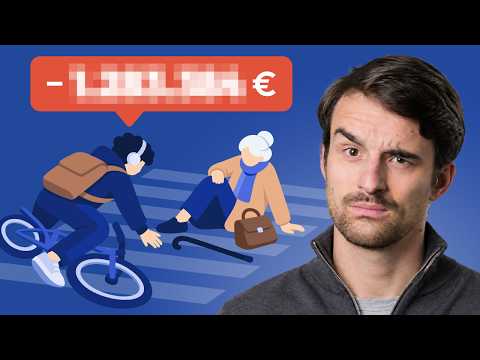
Do you really need it?- Yes, it is crucial for protecting against existential risks. Liability claims can quickly amount to hundreds of thousands or even millions of Euros.
- Passive legal protection: Your insurer defends you against unjustified claims (e.g., the Ingolstadt case).
- Counterargument: Low probability (approx. 4%). However, for an annual premium of around €50, the risk is too high to bear alone.
- Property damage, personal injury, and financial loss caused by negligence.
- Gross negligence (e.g., fire from a forgotten candle) is usually covered.
- Borrowed or rented items and neighborly favors are included in good policies.
- Unintentional damages in connection with criminal acts can be covered.
- Loss of recourse coverage: Pays if the culpable party is uninsured or insolvent.
- Rental property damage: Essential for tenants.
- Gradual damage: Damage occurring over months.
- Children incapable of tort: Coverage for damages caused by young children.
- Sum insured: At least €10 million, preferably €50 million.
- Key insurance: Covers lock replacement costs (up to €200,000).
- Best performance guarantee: Policy updates automatically to market standards.
- Price: Great tariffs are cheap. The best single tariff is approx. €41 per year.
- Single vs. Couple: A couple's tariff is cheaper, but inter-partner damage is often excluded.
- Deductible: A small deductible protects against policy cancellation for minor claims.
- Switching: Never cancel your old policy before the new one is confirmed.
- SCHUFA: If you have negative entries, try AXA or VHV.
Conclusion: Private liability insurance is a fundamental building block of financial security. Low cost, essential protection.