
2 min read
More Stocks To Buy - Quadrant Update November 2026 - Part 1
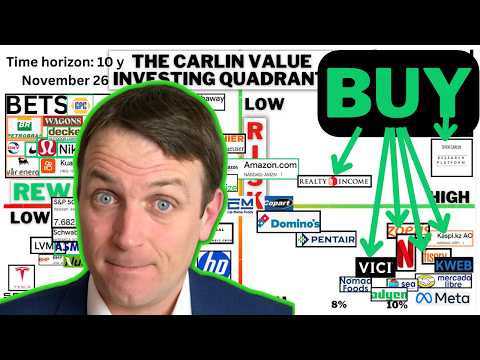
Quadrant Update November '26: Where do Risk and Return Stand?
The creator updates his value investing quadrant, focusing on recent quarterly results and market shifts.
Top Performers & Fundamental Strengths
- Fiserv: Despite a +24% price increase, the return perspective is improving thanks to higher savings and massively increased buybacks (7% buyback yield) at an attractive P/E ratio. Clear hold.
- Netflix: $11bn in free cash flow provides pricing power. Intrinsic value shows potential to double or triple the investment over 10 years. Moderate position with medium risk.
- Vici Properties: Stable cash flow from Las Vegas. 7% dividend plus 3% buyback yield a projected total return of 10%.
Tech Giants: Massive AI Bets
- Meta Platforms: Operating margins are collapsing due to massive AI investments ($700bn in commitments). Negative cash flows loom, financed by debt. Enormous risk, but if AI monetization succeeds, Meta is massively undervalued. An extreme high-risk, high-reward bet.
- Amazon: $42bn in negative free cash flow from investments. Intrinsic value is above the current price, making it no longer a bargain. Conservative 7% long-term return.
- Chinese Tech (Alibaba, JD, Tencent): A paradox: Dominant revenue growth but negative stock returns (Alibaba -11% over 14 years!). Rated as higher risk (geopolitical) by the creator, but with immense potential value.
Cycles & Downturns
- Cal-Maine Foods: The egg cycle is at rock bottom. Profits are a measly $403k. Past buybacks at peak prices were a mistake. The creator is waiting for an even lower market cap. "Wake me at a $3bn market cap."
- Pentair & Domino's: Prices rose, return expectations dropped from 10% to a fair 7-8%.
Conclusion: Extreme market divergence. While hyped US names (Meta, Amazon) are loved despite questionable cash flows, fundamentally strong Chinese values are hated and cheap. The creator sticks to his value compass. Part 2 with Mercado Libre, Zoetis, and Kaspi follows.


